Well, this is interesting. It also represents the largest buyback offer in its corporate history.
Utah Medical Products, Inc. (Nasdaq:UTMD) announces today that it intends to repurchase at a price of $75.00 per share up to 650,000 of its shares, if tendered and not withdrawn by stockholders on or before October 7, representing approximately 20% of its currently outstanding shares.
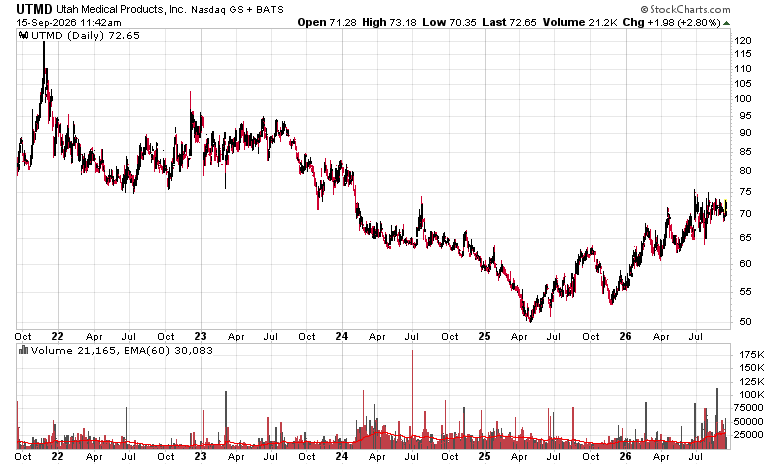
From their Q2-2026 filings, they have US$87.5 million cash on hand and 3.184 million shares outstanding. Reported net income for the first half of 2026 is $5.3 million; revenues are in decline. They announced on August 31, 2026 they purchased a 100% interest in a UK company distributing supplies for “harm reduction” for US$4.9 million equivalent, which will add US$6 million/year in revenues but also synergize distribution with another product line (the press release for this was quite silent on any income metrics).
The company is proposing a buyback of approximately 20% of its common shares for US$47.5 million, at US$75/share.
This is very out of character of management, which has tended to move glacially. They bought back US$20 million in stock in 2024 and $8.4 million in 2025, and about $0.2 million repurchased so far in 2026. Needless to say, this potential $47.5 million repurchase is a considerable deviation from their past trend.
I suspect management is receiving pressure from its institutional shareholders that they should be doing something with their cash stack (the company is considerably over-capitalized). Instead of issuing a US$15/share special dividend (which is what $47.5 million represents) they decide on a route that basically tells those shareholders “sell out or shut up”. It is also at a price that is quite tepid, which kind of describes this company as a whole.
My analysis of this firm from last year pretty much stands today. Something makes me think on the back of my mind that the crafty 79-year old CEO has a few more cards left to play beyond this buyback proposal.